Roof Insurance Guidance for Southlake, TX
Understand the difference between needed roofing work and a covered insurance payment, including deductibles and roof settlement terms.
Separate the roof work from the policy payment
A damaged roof raises two questions: what will repair it, and how much of that work the policy covers. Those answers can differ. A roof may need a broader physical repair than an owner expected, while a deductible or settlement term changes the amount paid by insurance.
This guide helps keep the conversations clear. Use roof findings to understand the work and the insurer’s policy explanation to understand payment. A local storm report, a visible dent or a roof’s age cannot replace either assessment.
What affects a roof claim payment
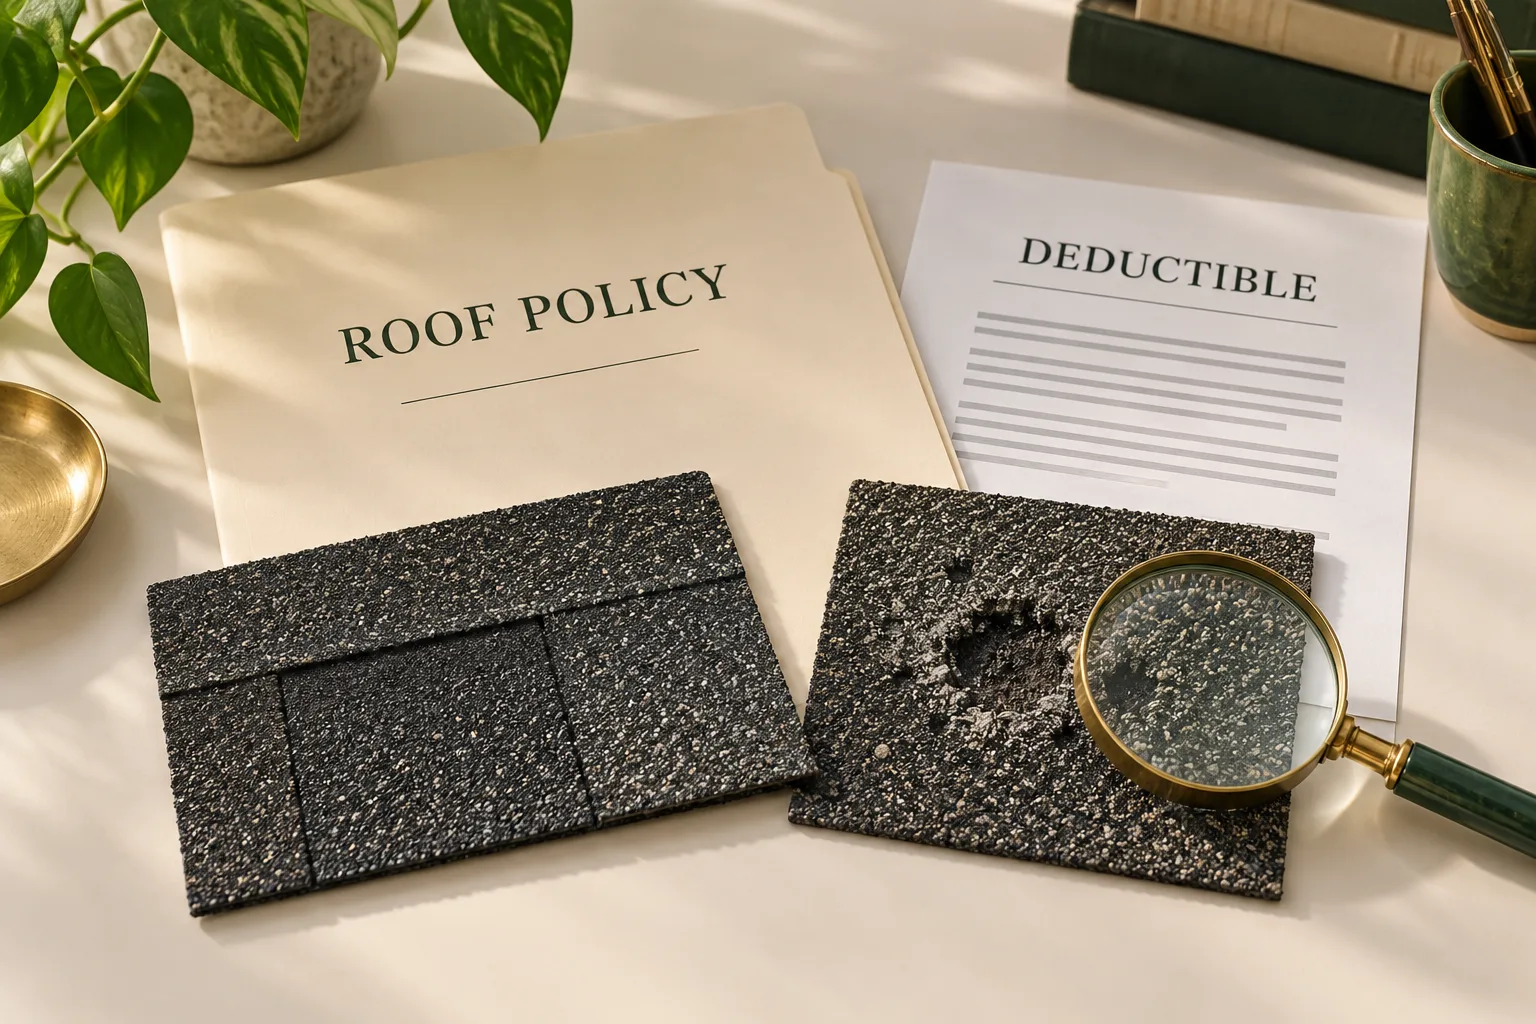
The Texas Department of Insurance’s roof insurance guidance distinguishes replacement-cost and actual-cash-value coverage and notes that a wind/hail deductible may differ from other deductibles. The actual policy controls your claim.
After roof damage
TDI’s claim-handling overview recommends prompt notice, damage records and retained expense receipts. Carry out those steps safely; a claim is not a reason to climb onto a damaged roof.
Protect people and limit further entry safely
Stay away from wet electrical areas, unstable ceilings and damaged roof surfaces. Discuss temporary roofing protection where conditions allow. Immediate danger requires emergency help before routine claim or roofing arrangements.
Notify the insurer and preserve useful information
Tell the insurer what happened and ask what it needs to assess the claim. Keep safe existing photos, relevant dates and receipts for temporary work. Note what was observed without assigning an unsupported cause to every mark.
Establish the roofing scope
The inspection identifies damaged material, surrounding condition and any further investigation needed. A focused repair and a wider replacement are different scopes; both should be explained by the roof condition rather than the hoped-for payment.
Resolve the payment and work arrangements
Direct policy and payment questions to the insurer or agent. If the scope differs from the insurer’s estimate, the underlying work and supporting information need to be understood. Agree the roofing contract, owner costs and optional changes with clear terms.
Roof insurance FAQs
Will insurance replace a roof just because it is old?
TDI explains that age or wear alone does not entitle a roof to replacement payment. Condition still matters to the roofing decision, but a claim needs to be assessed under the actual policy and cause of loss.
Must there be a ceiling leak before roof damage can be covered?
An indoor leak is not the only possible evidence of damaged roofing. The insurer considers the covered cause and policy terms; the roofer examines the condition of the covering and its connections. Neither a dry ceiling nor a nearby storm report settles the claim by itself.
Who pays for a more expensive shingle I choose?
A chosen upgrade may create a cost beyond the covered repair scope. Separate the physical repair needed from the optional material change, and confirm the payment implications with the insurer and the roofing contract.
Can a roofer decide what my policy owes?
The roofer can explain the roof condition and proposed work. The insurer handles the coverage and settlement decision under the policy.